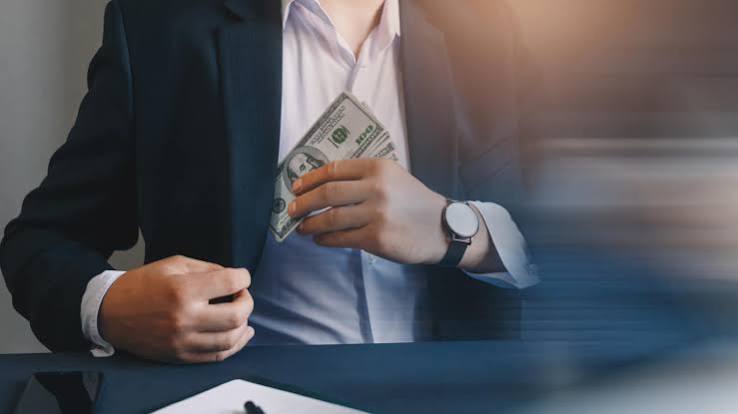

Every day, across the globe, fraudsters hoodwink individuals into handing over their hard-earned money. While public commentary routinely attributes these losses to sheer greed or financial illiteracy, behavioural science reveals a far more complex reality: even when participants recognize clear warning signs or have already suffered severe financial damage, they frequently refuse to walk away.
Beyond Greed and Financial Ignorance
Understanding why investors persist in fraudulent schemes requires looking beyond basic financial literacy to examine the psychological mechanisms that govern decision-making under stress. The fundamental question is not merely why people fall for Ponzi schemes initially, but why they continue participating long after the danger becomes glaringly obvious.
“Sometimes, the biggest risk to an investor is not that they cannot recognize a bad investment. It is that they cannot bring themselves to abandon one.”— ABT News Behavioural Insights
Five Behavioural Mechanisms Explaining Persistent Participation
| Mechanism | Psychological Mindset | Observed Behavioural Impact |
| 1. Sunk Cost Fallacy | “I have invested too much to walk away now.” | Commits fresh funds to “unlock” delayed payments rather than accept an unrecoverable loss. |
| 2. Loss Aversion | “I would rather keep trying than accept the loss.” | The pain of losing money drives irrational risk-taking to recover capital, eclipsing prudent protection. |
| 3. Overconfidence & Control | “I know the risks and I know when to get out.” | Believes they can predict the scheme collapse and exit early, misinterpreting early payouts as personal judgment. |
| 4. Cognitive Dissonance | “The warning signs are not as bad as they appear.” | Rationalizes withdrawal delays as temporary glitches to protect their ego and social reputation. |
| 5. Social Proof | “Others are still investing, so I must be wrong.” | Relies on community chat groups and peer payout screenshots to validate remaining in the scheme. |
Why Financial Literacy Alone Is Insufficient
Conventional investor protection operates on the assumption that educating the public on how Ponzi schemes operate will automatically prevent participation. However, knowledge rarely overrides deeply ingrained cognitive biases.
An investor can easily recognize that unusually high guaranteed returns are mathematically impossible, yet still participate due to overconfidence in their timing. Another may clearly identify withdrawal holds as a critical red flag, but remain locked in due to loss aversion and the emotional cost of admitting a mistake to family and friends.
Redesigning Investor Protection Frameworks
For financial advisers, safeguarding clients requires identifying not just market risks, but the psychological triggers that prevent individuals from cutting their losses. For regulators, it highlights the necessity of designing protection strategies centered on actual human behaviour rather than theoretical rationality.
ABT NEWS Reader Inquiry
- Have you or someone you know ever participated in a scheme despite recognizing early red flags?
- What psychological or social factor made it most difficult to walk away? Please send your experience to editor@abtnews.net

 By